IJSS
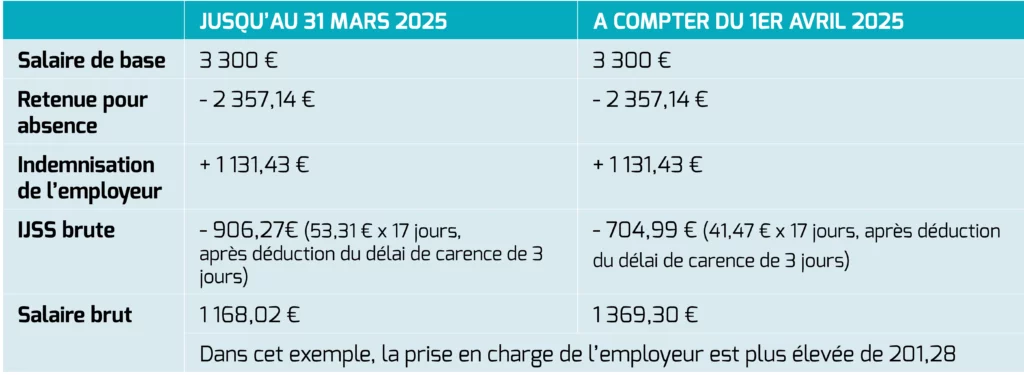
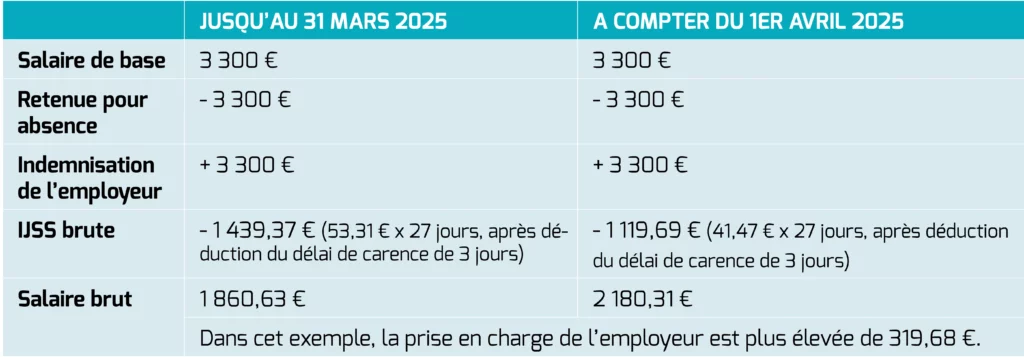
For work stoppages starting on or after April1, 2025, the calculation of IJSS sickness benefits will be capped at 1.4 SMIC, compared with 1.8 SMIC at present. As a result, sick pay will automatically fall for employees earning more than 1.4 SMIC.
An employee is absent for 20 calendar days (15 working days) in a month with 147 hours worked.
Example 2: salary maintenance with additional compensation of 100% of gross salary with no waiting period:
Aid for hiring apprentices
Find out more about possible grants for hiring an apprentice.
PPV and savings plan: your savings plan regulations must be updated
As indicated in our previous news, employees can now pay their PPV into a savings plan, with the advantage that the sum obtained is tax-free for certain employees.
Imperative formalism :
In order to maintain the favorable tax and social security treatment of amounts saved in a savings plan, the company must update the savings plan regulations with information on :
- The possibility of allocating the sums collected under the PPV (specifying the sources of funding for these plans).
Tolerance: For practical reasons, amounts paid up to June 30, 2025 under the PPV may be allocated to the various plans even before they are modified.
- Terms and conditions of top-up payments, if required
Please note that in the absence of any reference to a possible top-up in the event of payment by employees of the PPV, no top-up is possible.
Note beforehand and as a reminder: Employees must be informed of the allocation or immediate availability of their funds at the time of each payment. However, it may be acceptable for this information to be requested only once a year, at the time of the 1st payment. Nevertheless, after each payment, the employee has the option of changing his or her initial choice for the following payment. The employer must inform the employee of this at the time of the 1st payment.
Other note: In the absence of an express choice by the employee, the bonus is paid to him/her. It cannot be allocated to a savings plan by default.
- Conditions for unlocking the PPV upon allocation to a savings plan :
When the PPV is allocated to a savings plan, it has the nature of a voluntary payment.
The employee cannot reverse his or her choice. The bonus may not be withdrawn from the plan before the lock-in period stipulated in the plan (5 years or retirement), except for a reason allowing early release of the sums invested. Only assets held in the employee savings plan prior to the triggering event may be released.
Benefits in kind vehicle retroactive application to 01022025 according to the decree of 02/25/25 PUBLISHED in the JO 02/27/2025
A decree dated February 25, 2025 reforms the valuation of benefits in kind, marked by a sharp increase in flat-rate benefits for combustion-powered vehicles and the retention of benefits for electric vehicles.
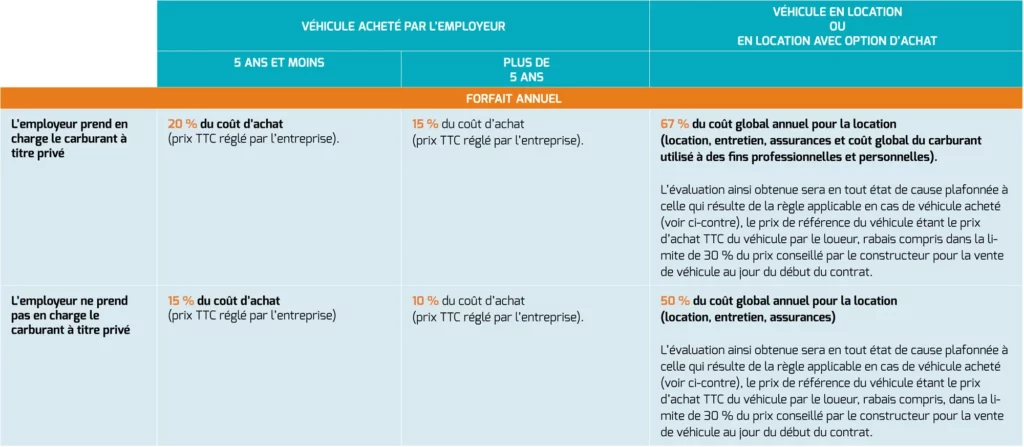
Benefits for electric vehicles. - The specific allowance for exclusively electric vehicles (excluding hybrids) has been renewed, and the rate has been increased.
As a reminder, this allowance expired on December 31, 2024.
For 100% electric vehicles(made available between February1, 2025 and December 31, 2027), the benefit in kind is valued after a 70% allowance, capped at €4,582 per year.
For 100% electric vehicles made available until January 31, 2025, the allowance is set at 50%, up to a maximum of €2,000.30.