The Action Plan for Business Growth and Transformation (Loi PACTE enacted on May 22, 2019) aims to remove obstacles to business growth, at all stages of development: from start-up through financing to handover.
The PACTE Act has radically overhauled the statutory audit.
Appointment of the Statutory Auditor
Any commercial company that exceeds two of the three thresholds: 4 million euros in total assets, 8 million euros in sales excluding tax, 50 employees (4/8/50) on an individual basis must appoint a statutory auditor for 6 financial years.
Appointing the statutory auditor for small groups
The Pacte Act introduced an obligation for "small groups" to appoint a statutory auditor (CAC).
Explanations and obligations :
Small group
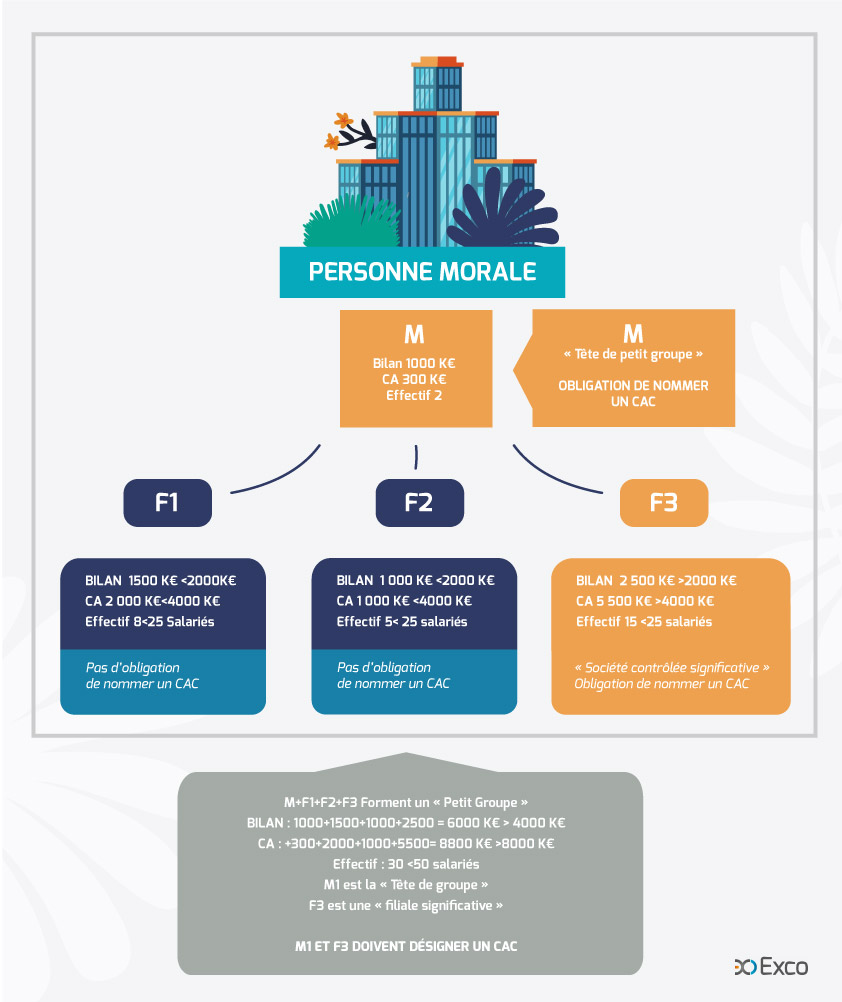
A " small group" is a group formed by a person or entity that is not a PIE (public-interest entity) and is not required to publish consolidated financial statements, that controls one or more companies within the meaning of Article L 233-3 of the French Commercial Code, and that exceeds two of the following three thresholds:
- 4,000,000 € balance sheet total,
- 8,000,000 in sales excluding tax
- 50 employees (C. com. art. L 823-2-2 and D 823-1).
(Aggregate figures from the most recent annual financial statements, without pro-rating or elimination of intercompany transactions) :
Small group leader
The "head of a small group" may be an individual or a legal entity. In the case of a legal entity , it must appoint a statutory auditor.
Significant controlled companies
Controlled companies belonging to this "small group" must appoint a CAC when 2 of the 3 following thresholds are crossed:
- 2,000,000 € balance sheet total,
- 4,000,000 in sales excluding tax,
- 25 employees.
Examples of CAC appointments
- Exceeding two of the three following thresholds: 4/8/50
- Exceeding two of the following three thresholds: 2/4/25